An Edinburgh return, worked through
Three fictional bookings show what to check before you prepare a return. This is an illustrative example, not a customer testimonial or an official submission.
The starting records
One property, GBP, no VAT registration, no extras or separate cleaning fees, and a constant £100 accommodation rate per night. All bookings and first payments are after the transitional cutoff. All stays are wholly within August 2026.
| Booking | Accommodation | Collected | Expected | Difference |
|---|---|---|---|---|
| DEMO-001 · 3 nights | £300.00 | £15.00 | £15.00 | £0.00 |
| DEMO-002 · 8 nights | £800.00 | £40.00 | £25.00 | +£15.00 |
| DEMO-003 · cancelled | £200.00 | £10.00 | £0.00 | +£10.00 |
Review the two differences
- Eight-night stay: at a constant nightly price, the first five nights produce £25 of levy. The £40 collection needs investigating; do not quietly substitute the payout figure.
- Cancellation: no stay took place. Check the tax refund record and keep evidence of the correction. The £10 collection must not disappear merely because the reservation is marked cancelled.
The source reports £65 collected against £40 expected. That £25 difference is a review item, not proof a refund or a council payment has happened. At the example’s 2% provider retention, £0.80 is retained and estimated net levy is £39.20. Compare collection with £40 gross levy, not £39.20 net.
See the calculation in the product
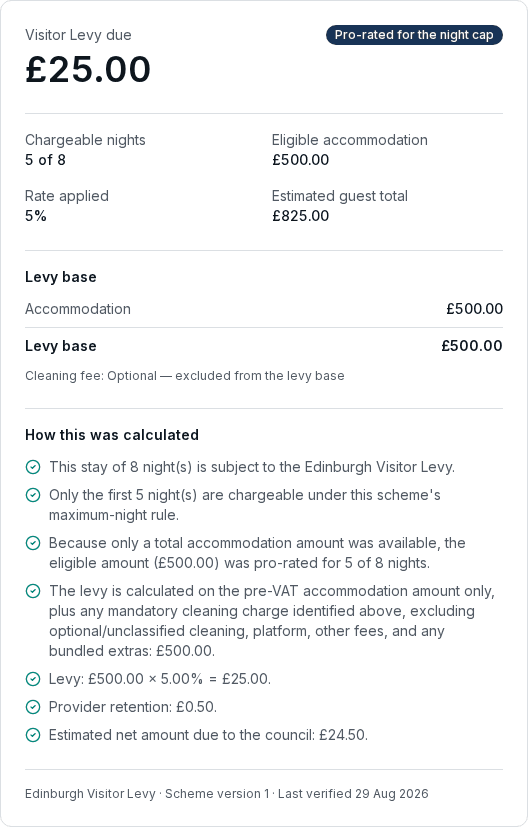
The public calculator produces £25 for the example’s eight-night, £800 stay. Its breakdown shows the five-night cap, £500 levy base and £0.50 provider retention.
Try the same records
Download the three sample bookings, preview them in an account set up for testing, and inspect the per-booking calculation. Do not mix fictional records into a live return. The example totals are also checked against the application’s calculation engine in automated tests.
Prepare the actual submission
Review monthly figures, availability, exemptions and any missing bookings against your source systems. Submit through visitorlevy.scot, then keep the submission and payment references. This example covers only three records and cannot establish the completeness of a real quarter.
Rules checked 20 September 2026 against Edinburgh’s accommodation provider guidance.